I am not only a local Realtor. I was born and raised in Pacific Palisades. My parents still live here. The friends I grew up with on these streets are the same families now deciding whether to rebuild the houses we spent our childhoods in, or to sell and start again somewhere else. When something changes the math on that decision, I do not think of it as market news. I think of it as something my friends, my family, and my clients need to hear from me first, clearly and without a sales pitch.
This is one of those moments.
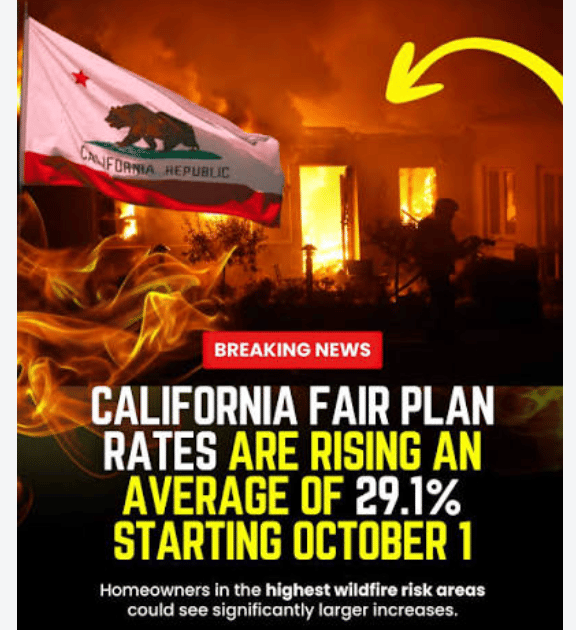
On October 15, 2026, California FAIR Plan rates rise by an average of 29.1%. The increase lands just weeks after Governor Newsom signed the country's first smoke-damage testing and remediation standards into law, and in the same week our community broke ground on a new Palisades Recreation Center. Taken together, these three developments change the carrying-cost equation for every owner in the Palisades, Topanga, and the upper Santa Monica Canyon corridor.
Below is what is changing, who it affects most, and how I am helping families work through the question underneath all of it: rebuild, or sell.
1. The FAIR Plan Increase: What Is Actually Changing on October 15
The California FAIR Plan is the state's insurer of last resort. For many Westside homeowners in high wildfire-risk areas, it has become the only fire policy available after traditional carriers stopped writing or renewing.
Here are the confirmed facts:
- The increase: An average of 29.1% statewide. The FAIR Plan originally requested 35.8%; the California Department of Insurance reduced it.
- Timing: It applies to FAIR Plan policies written or renewed on or after October 15, 2026. If your renewal falls after that date, your next bill reflects the new rates.
- Who pays more: The increase is an average, and averages hide a lot. Reporting from KQED and United Policyholders indicates that some policyholders in lower-risk areas will actually see reductions, while roughly half will see increases in the range of 30% to 50%. In the highest-risk areas, some premiums could double.
- How many people it touches: More than 675,000 California customers now rely on the FAIR Plan, roughly 5% of homes in the state, up from under 2% only a few years ago.
To put the average in plain numbers: a household paying $10,000 a year in FAIR Plan premium would pay roughly $12,910 after an average increase. That is before the separate "difference in conditions" (DIC) policy most owners carry to cover theft, liability, water damage, and loss of use, which the FAIR Plan does not include.
Why it matters here more than almost anywhere else. The steepest increases concentrate in high wildfire-risk and wildland-urban interface (WUI) areas. That describes much of the Palisades rebuild footprint, the Topanga Canyon community, and the upper reaches of Santa Monica Canyon. Our neighborhoods are exactly where this lands hardest, and it arrives before most families have finished their 2026 planning.
2. What the Increase Does to the Rebuild-or-Sell Math
Every family I sit down with in the Palisades is working through some version of the same equation. The FAIR Plan increase does not change the question, but it changes several of the numbers inside it.
If you own a burned lot and are still deciding. Your carrying costs today are property taxes, any remaining mortgage, and liability coverage on the vacant land. The moment you start construction, you add builder's risk coverage. The moment you finish, you need a full homeowners program on a newly built house. The October 15 increase raises the long-term cost of that final stage, which means it belongs in your rebuild budget now, not after the certificate of occupancy.
If your home is standing and you are insuring through the FAIR Plan. Your annual cost of ownership is going up, and that change flows directly into what a buyer will be willing to pay. Buyers underwrite insurance the way they underwrite interest rates. A home that is documented, hardened and insurable at a reasonable cost is simply a more valuable home than an identical one that is not.
If you are planning to sell in the next twelve months. A buyer's lender will require proof of insurance before closing. Higher premiums narrow the pool of buyers who can comfortably carry a Palisades home, particularly at the upper end, where Measure ULA's transfer tax already adds friction to net proceeds. Pricing strategy has to account for the buyer's total monthly cost of ownership, not only the purchase price.
Where new construction has an edge. A home rebuilt today is built to current Chapter 7A wildfire standards, with ember-resistant vents, Class A roofing, and noncombustible materials designed in from the beginning. Those are the same features insurers look for, and the FAIR Plan itself offers discounts for many of them. In a market where insurance has become a major line item, a new house built to modern fire code is a distinct and increasingly valuable product.
3. The New Smoke-Damage Law: A Turning Point for Standing Homes
On September 15, 2026, in Altadena, Governor Newsom signed a wildfire recovery package that includes two bills our community has been waiting on.
- AB 1642 (Assemblymember John Harabedian) establishes the nation's first standards for testing and remediating lead and asbestos contamination from wildfire smoke in homes within fire zones. The Department of Toxic Substances Control must set standards for lead and asbestos by the end of 2028, and for heavy metals and other pollutants by the end of 2029. Insurers are required to cover these costs and cannot cut off Additional Living Expense coverage until a home is remediated and safe.
- AB 1795 (Assemblymember Mike Gipson) requires insurers to follow those scientific standards and places the burden on the insurer to show a home is safe, rather than on the family trying to go home.
Assemblymember Harabedian put it simply: "Science, not an insurance company's opinions, will determine whether a home is safe."
The same package included two mortgage protections that matter for families still carrying a loan on a damaged or destroyed home:
- AB 1847 doubles the mortgage forbearance window for Los Angeles fire survivors from 12 to 24 months and requires servicers to offer deferral of missed payments until the end of the loan.
- AB 1842 creates permanent mortgage forbearance protections after future disasters.
Why this is real estate news. Roughly 13,000 smoke-damage claims were filed after the January 2025 fires. Many of those homes are standing but frozen: not livable, not resolved, and very hard to sell because no buyer can underwrite an unknown. A defined, science-based standard gives those homes a path to resolution. Over time, that should bring some of that frozen inventory back to market with a clean record, and it gives buyers something concrete to evaluate instead of a guess.
If you are one of the families living this, I would encourage you to speak with your public adjuster or attorney about how the new law applies to your specific claim. I am happy to connect you with people I trust.
4. Speed Matters More Now: The Standard Plan Program
Every month a lot sits unbuilt is another month of carrying costs, and the FAIR Plan increase makes those months more expensive. That is why the fastest path to a permit deserves a serious look.
The City of Los Angeles Standard Plan Pilot Program offers a library of pre-approved, code-compliant single-family home designs already reviewed by the Department of Building and Safety. An owner who selects one of these plans can move directly to permit issuance without the traditional plan-check process. The city has reported Palisades permits moving nearly three times faster than the pre-fire baseline, with more than 70% of the clearances a single-family permit used to require no longer necessary. The library continues to expand on a rolling basis, and Mayor Bass's office continues to announce new approvals under the program.
A standard plan is not the right choice for every family. Many of my friends grew up in houses with a particular character, on lots with a particular view, and they want to rebuild something personal. But for an owner who wants to be home sooner, or who wants to hold down design costs and months of carrying expense, a pre-approved plan can change the timeline substantially. If you are weighing a custom build against a faster, pre-approved path, this is the moment to raise it with your architect.
It is also worth remembering the deadline window under the city's emergency order. As builder Eddie Lorin has written in the Palisadian-Post, the order provides a generous period to pull a permit and complete construction, but it is not unlimited. An entitled lot with approved plans and an unentitled lot are increasingly priced as two different assets.
5. A Simple Framework: Rebuild, Sell, or Hold
When I sit with a family, we lay out both paths side by side. These are the questions I walk through:
- What does your insurance recovery actually total? Dwelling coverage, extended replacement cost, code upgrade coverage, debris removal, and Additional Living Expense all affect how much of a rebuild is funded. The new smoke-damage law may also change the picture for standing homes.
- What will it cost to build what you want? Hard costs, soft costs, site work, permits, and financing, compared against a realistic finished value for your street, not a town-wide average.
- What will it cost to carry the property until it is done? Property taxes, mortgage, builder's risk coverage, and now a higher long-term insurance cost after completion.
- What is your land worth today, and what will it be worth once entitled? Street, slope, view, lot size, clearance status, and permit status all move value.
- What does selling net you? Lot value minus commissions, closing costs, and, above the thresholds, Measure ULA.
- What is your timeline, and what is your family's tolerance for a multi-year construction process? This one is personal, and it matters as much as any number.
- What do your tax and legal advisors say? Questions about property-tax basis, capital gains, and trusts belong with your CPA and attorney before any final decision.
There is no universally right answer. I have friends who are rebuilding and could not be happier with the decision, and friends who sold and are at peace with that choice. My job is to make sure the decision is based on real numbers, current law, and an honest read of the market.
6. What I Recommend Doing Before October 15
- Find your renewal date. If it falls on or after October 15, the new rates apply to you.
- Call your broker now. Ask for current quotes from the FAIR Plan and any admitted or surplus-lines carriers writing in your ZIP code. Recent reporting indicates Mercury, Farmers, and CSAA have been writing some new business under the state's Sustainable Insurance Strategy, and Mercury resumed writing in Topanga this summer.
- Document every hardening improvement. Photographs and receipts for a Class A roof, ember-resistant vents, enclosed eaves, dual-pane windows, and a five-foot ember-resistant zone can qualify for FAIR Plan mitigation discounts. The Department of Insurance's Safer from Wildfires program lists the qualifying measures.
- Review your DIC policy. Confirm it provides replacement cost, adequate loss-of-use limits, and meaningful liability coverage. Do not reduce liability or loss-of-use coverage to save on premium.
- Right-size your dwelling limit to reconstruction cost, not market value.
- If you are carrying a mortgage on a damaged or destroyed home, ask your servicer about the new 24-month forbearance window under AB 1847.
- Run the rebuild-versus-sell numbers with the new premium included. If you would like, I will do this with you.
7. The Town Is Coming Back, and That Belongs in the Math Too
Numbers explain a lot, but they do not explain everything. What tells me where we really are is who is showing up and what is being built.
On September 15, Mayor Karen Bass, Councilmember Traci Park, Rick Caruso of Steadfast L.A., Lakers head coach JJ Redick of L.A. Strong Sports, and Recreation and Parks General Manager Jimmy Kim broke ground on the new Palisades Recreation Center. The philanthropically funded project, described as the largest public-private partnership in the history of Los Angeles parks, is expected to take roughly 14 to 16 months and includes indoor basketball and pickleball courts, a two-level playground, a youth soccer field, bocce courts, community rooms and a Veterans Garden. Councilmember Park said it best: the Rec Center was always the heart of the Palisades, and generations of kids played there.
The Recreation and Parks commissioners also approved moving the Palisades baseball fields to artificial turf. The Pacific Palisades Community Council approved a two-year strategic plan. Paliskates, which has outfitted Palisades kids for more than two decades, is working toward an early 2027 return. And in the Palisadian-Post, builders Matt Steele and Jane Kim Keener continue writing practical, step-by-step guidance for families managing their own rebuilds, from rough-in inspections through project closeout.
These are the hometown heroes of this recovery: the families, business owners, volunteers, and neighbors who decided this place was worth coming home to. Every one of them is part of why I believe a completed home in the Palisades will be worth more, not less, as the town fills back in.
Frequently Asked Questions
When does the California FAIR Plan rate increase take effect? The average 29.1% increase applies to FAIR Plan policies written or renewed on or after October 15, 2026.
Will every Pacific Palisades homeowner see a 29.1% increase? No. 29.1% is a statewide average. Some policyholders in lower-risk areas will see reductions, while many in high wildfire-risk areas, including much of the Palisades, Topanga, and upper Santa Monica Canyon, may see larger increases. Your broker can give you your specific renewal figure.
Can I lower my FAIR Plan premium? Documented wildfire-hardening measures, such as a Class A roof, ember-resistant vents, enclosed eaves, dual-pane windows, defensible space and a five-foot ember-resistant zone, can qualify for FAIR Plan discounts. Firewise USA community designation can qualify as well. Shopping admitted and surplus-lines carriers through an independent broker is also worthwhile.
What does the new smoke-damage law do for Palisades homeowners? AB 1642 and AB 1795, signed September 15, 2026, create the nation's first science-based standards for testing and remediating wildfire smoke contamination, require insurers to follow them and cover the costs, and bar insurers from cutting off Additional Living Expense until a home is safe to reoccupy.
Should I rebuild or sell my Pacific Palisades lot? It depends on your insurance recovery, construction budget, carrying costs, land value, timeline and tax situation. The FAIR Plan increase raises the long-term cost of ownership, and the Standard Plan Program can shorten the time to a permit. I run both scenarios side by side, with current numbers, for any owner who asks.
How fast can I get a rebuild permit in the Palisades using a standard plan? Pre-approved standard plans skip the traditional plan-check process and move directly to permit issuance. The city has reported Palisades permits moving nearly three times faster than the pre-fire baseline.
How does the FAIR Plan increase affect Palisades home values? Buyers factor insurance into their monthly cost of ownership. Homes that are newly built to current wildfire code, or documented and hardened, are easier and less expensive to insure, which supports stronger pricing relative to comparable homes without those features.
Where I Come In
I have spent my career in Westside luxury real estate, and I have spent my life in this town. I know these streets because I grew up on them. I know the families because many of them are my own friends and neighbors, and some of them are family.
After the fire, I made myself a promise: to help the Palisades become a genuine place for generations again, as it was before, the town we remember. For me, that starts with making sure the people I care about have accurate, current information before they make one of the biggest financial decisions of their lives. It is an honor to help my neighbors rebuild, and it means a great deal to me every time I see another family find their way home.
If you are deciding whether to rebuild or sell, trying to understand what the FAIR Plan increase means for your property's value, or considering a move into the Palisades, Topanga or Santa Monica Canyon, I would be glad to sit down with you.
Visit jocelynkelleyrealestate.com for current market reports and neighborhood guides, request a confidential valuation at jocelynkelleyrealestate.com/home-valuation, or reach me directly at (310) 963-2524 or [email protected].
For the complete picture on permits, insurance, new laws, and home values, read my ongoing guide: Pacific Palisades Real Estate 2026: Rebuild Progress, Insurance and Home Values.
About the Author
Jocelyn Kelley | DRE #01447462 | Licensed since 2007 Berkshire Hathaway HomeServices California Properties — Chairman's Circle Gold, Top 2% of approximately 50,000 BHHS agents worldwide; Leading Edge Society. Born and raised in Pacific Palisades, with multi-generational family ties to the community, Jocelyn represents buyers and sellers across Pacific Palisades, Santa Monica, Malibu, Brentwood, Topanga, Venice, Marina del Rey, Mar Vista, Culver City, Beverly Hills, and Westchester. Office: 3130 Wilshire Blvd, Santa Monica, CA 90403.